A full house and still in the red? Many operators know this dilemma: the restaurant is busy, the guests are happy – but at the end of the month there is hardly any profit left. Why? Prices are often still calculated by gut feeling or with outdated percentage mark-ups. At a time of soaring costs (food, staff, energy), that is no longer enough. This is where contribution margin costing comes in. It focuses on how much money each dish or drink sold actually contributes to covering fixed costs, instead of just aiming for a percentage margin. Industry experts already call this method the “fairest pricing” – every guest bears an equal share of the overheads – and advise operators to switch consistently to contribution margin as soon as possible. In this article you’ll learn, with a practical focus, why concentrating on contribution margin makes business sense, and how BarBrain’s recipe management with up-to-date ingredient costs gives you the basis for it.
Percentage margin vs. contribution margin: what’s behind it?
For a long time, selling prices in hospitality were calculated with simple mark-ups – for example cost of goods times a factor of 3 or 4. That’s simple, but it has pitfalls. Why? Because percentages alone are often misleading. An example: a beef fillet for €25 may have a cost of goods of over 30%, but still delivers an absolute contribution margin of around €10–15. A salad for €8, on the other hand, has a cost of goods below 30%, but only brings in around €4–6 of contribution margin. The more expensive item generates more profit in euros, even though its percentage margin looks worse. Looking only at percentages falls short – what matters is how much money is left at the bottom line.
Traditional mark-up calculations ignore important factors. Products with a low cost of goods end up being offered extremely cheaply and generate only a small absolute profit; at the same time, cost-intensive dishes become very expensive and may sell less well. The result: your most popular dishes – the so-called “bestsellers” – sometimes turn out to be losers in business terms, because despite high sales volumes they contribute hardly anything to covering costs. Conversely, some high-priced specialities (“sleepers”) cannot make up for the bestsellers’ losses despite a decent profit per unit, because they are only rarely ordered. In short: a purely percentage-based calculation can mean that you still earn too little despite full tables.
Contribution margin costing addresses exactly this. For every item, it asks: how much is left to cover my fixed costs? And this contribution margin (CM) is considered as an absolute amount in euros, not as a percentage of the price. This finally takes into account the sharply increased staff and overhead costs of recent years – something the old rules of thumb usually miss. More and more operators are realising: focusing on contribution margin creates transparency and enables fair, profitable pricing. Instead of unknowingly losing money on popular plates, you actively make sure that every dish makes an appropriate contribution to your operating result.
The logic of contribution margin costing: every guest helps carry the fixed costs
What exactly is contribution margin? Put simply: contribution margin = selling price – variable costs (cost of goods). This amount is then available to cover fixed costs – rent, salaries, energy, insurance, etc. – and ideally to make a profit. The logic behind CM costing is therefore: sum of all contribution margins = sum of all fixed costs + profit target.
How do you distribute the fixed costs fairly across guests? One approach is to determine the required contribution margin per guest. Divide your monthly fixed costs by the average number of guests – the result is the target contribution margin per guest that must be generated at a minimum for you to break even. Example: if your fixed costs are €16,000 per month and you serve around 1,500 guests, each guest has to bring in around €10–11 of contribution margin on average for the fixed costs to be covered. With this figure you can now calculate backwards: which prices and product combinations ensure that, on average, €10–11 per guest is left over?
In practice, contribution margin costing means setting your prices so that every dish on offer delivers a certain fixed contribution margin. For main courses in particular, a uniform target contribution margin is often set. Whether the guest orders an expensive steak or a simple pasta – every main course should, for example, yield €10 of contribution margin. The guest with the cheaper dish then ultimately pays the same contribution towards overheads as the guest with the expensive dish. The difference shows only in the selling price: a more elaborate, expensive dish gets a lower percentage mark-up, a cheap dish a higher one. At the bottom line, the venue earns the same amount on each of these dishes, which is considered particularly fair. After all, it is no longer ingredient costs that make up the bulk of expenses, but above all staff and rent – so all dishes should bear these overheads equally.
This approach requires some calculation at the start, but it makes costing more precise and future-proof. All actual operating costs feed into pricing. That protects you from surprises: if, for example, energy costs rise or wages go up, you see immediately whether the contribution margin you’ve set per dish is still sufficient – or whether prices need to be adjusted. In short, CM costing gives clarity on the profitability of every offer and prevents cross-subsidised loss-makers on the menu.
Practical examples: main courses, drinks and desserts compared
Let’s look at some concrete examples to make the difference between percentage margin and absolute contribution margin tangible:
Main course (high-priced): Let’s compare two main courses. Dish A costs €8 to prepare (cost of goods) and sells for €25. Dish B costs only €2.50 in ingredients and is offered for €9. Traditionally you might say: dish B is more profitable, because its cost of goods is only ~28% of the price, while dish A’s is ~32%. But look at the contribution margins: dish A generates €17 CM, dish B just €6.50 CM. Despite its higher costs, the more expensive dish delivers more than twice the profit contribution. This example shows impressively why the absolute margin in euros is decisive – not the cost-of-goods percentage. High-quality dishes with expensive ingredients in particular can (and may) have a lower percentage mark-up, as long as their contribution margin in euros is right.
Drinks: In many venues, drinks are used as real profit drivers. No wonder – the percentage mark-ups are often highest here. Example: a soft drink sold by the glass for €4 may have a cost of goods of €0.50. That gives a contribution margin of €3.50, i.e. a margin of 87.5%. Alcoholic drinks usually show an impressive CM ratio too. Many operators use this strategically: they price popular main courses relatively tightly (lower CM), but bring in the overall profit through high contribution margins on drinks. That way a cheap schnitzel can stay on the menu and attract guests, while sales of beer, wine & co. provide the necessary return. What matters is keeping an eye on the overall result – the key word is mixed costing. At the end of the day, the sum of food and drink contribution margins per guest has to add up.
Desserts & extras: Sides and desserts also contribute to the contribution margin. A dessert for €6 may have a cost of goods of €1.50 and thus contribute €4.50 to profit – often about as much as a main course. If the dessert is skipped, however, exactly this contribution is missing for that guest. That’s why it pays to actively sell desserts or put together set menus. The same applies to other revenue drivers such as coffee or a digestif at the end: every additional sale increases the contribution margin per guest. So if you notice that some guests contribute too little with a single main course (and tap water), you should review your sales strategies – e.g. recommending starters, desserts or premium drinks. Not to fleece guests, but to make sure every table experience delivers a fair economic return.
The examples make it clear: high-priced dishes with a moderate percentage margin can be more valuable than supposed “cash cows” with a high margin when you look at absolute returns. And every order – from main course to espresso – counts. By focusing on contribution margins per item and per guest, you can see exactly which parts of your offer are profitable and which aren’t. This lets you optimise menus in a targeted way: unprofitable items are adjusted or removed, profitable ones actively promoted.
Support from modern tools: recipe management and ingredient costs
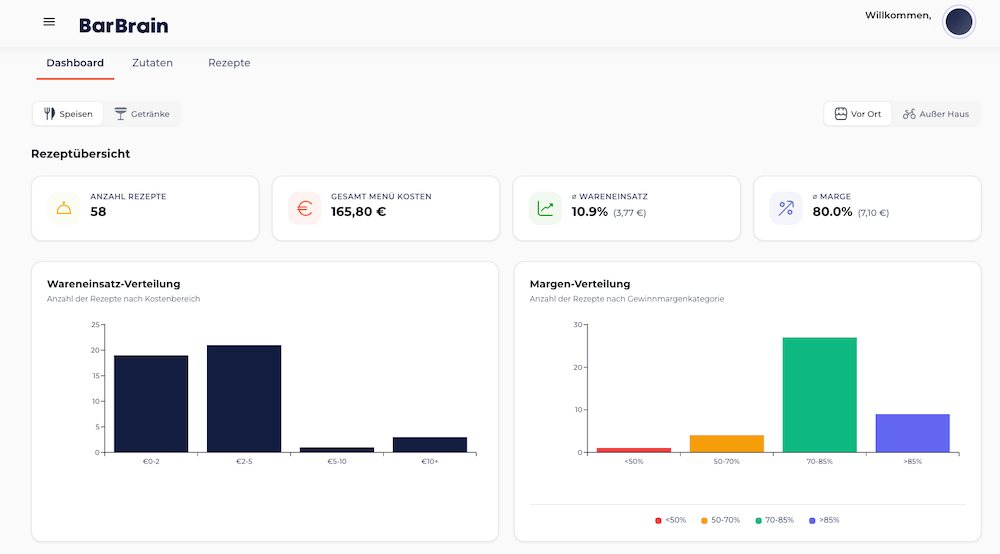
In theory this all sounds logical – but nobody wants to recalculate every recipe every day with a calculator and an Excel list. Fortunately, there are digital helpers today that make contribution margin costing much easier. Modern recipe management software such as BarBrain’s recipe management (available as an add-on for €29 per month) takes a lot of work off operators’ hands. In such tools you set up the recipe for every dish and every drink with exact ingredient quantities. From this, the system automatically calculates the current ingredient costs (cost of goods) per portion and their share of the selling price. You derive the contribution margin directly from this: selling price minus cost of goods. If purchase prices change, the costing is updated immediately – so you always know what each product really costs.
Even more important: if you calculate the contribution margins per item on this basis, you can see which items deliver the largest contribution margins and which lag behind. An item contribution margin analysis might show, for example, that your bestselling dish sells often but perhaps only brings in €3 of contribution margin – while a less frequently ordered dish brings in €8. Insights like these are worth their weight in gold. They enable data-based decisions: what to do with the “weak” bestseller? Perhaps reduce the portion size or raise the price moderately so that the CM rises without putting guests off. Or deliberately support bestsellers with low CM with additional sales (e.g. sides, drink recommendations) to increase the average bill. Conversely, you also identify slow sellers with a good contribution margin – here you could try to increase sales through marketing.
Digital tools like BarBrain give you the basis for this: recipes with up-to-date ingredient costs and regular stocktakes go hand in hand. If stocktakes are done regularly, you can spot, for example, variances between theoretical and actual consumption, which can point to incorrectly costed recipes or shrinkage. Such data is also extremely valuable for CM costing: a dish that would have a contribution margin of €5 on paper may bring in less in reality because the kitchen portions too generously – you can see that in stocktake differences. A good recipe manager (possibly linked to the POS and stock management) makes such gaps visible so that you can take targeted action. Overall, the advantage of digitalisation is that you can react faster: price changes, new recipes or supplier prices – all of this can be entered into software immediately, and you see the impact on your costing straight away. This turns contribution margin accounting from a one-off effort into a continuous controlling tool that gives you clarity about the health of your business at any time.
Current trends: contribution margin as a success factor
It’s no coincidence that contribution margin has become a buzzword in the hospitality scene. In podcasts, webinars and trade articles, industry insiders preach the benefits of this metric. Hospitality consulting influencers such as Kemal Üres, the “Gastroflüsterer” (hospitality whisperer), or F&B experts like Uwe Ladwig promote the CM approach as a modern must. Numerous venues have switched to contribution margin costing in recent years. If you consistently cost by contribution margin, you eliminate silent losses and can make better-founded pricing decisions. In a sector characterised by tight margins, that gives you a real competitive advantage.
This is not about driving prices sky-high – it’s about clarity and control. If you know your numbers, you can make conscious strategic decisions: perhaps you keep a popular burger on the menu for €9.90 even though it only brings in €5 CM – because you know that with sides and drinks you’ll still reach your target contribution margin for that guest. Or you decide to take an item that is elaborate to cook off the menu because, despite its high price, its contribution margin is negative once staff time is factored in. All of this requires you to know your contribution margins per item and overall. The trend in successful hospitality is heading exactly in this direction: away from rough rules of thumb, towards precise number-based thinking that stays close to day-to-day practice.
Finally, it’s worth looking at why contribution margin is also psychologically the metric of the moment. It creates urgency and focus. While a percentage margin is abstract and easy to gloss over (“30% food cost, that’s fine”), an absolute contribution margin shows mercilessly what is left at the bottom line. €3 profit per schnitzel – is that enough to carry your venue? If not, you know exactly what to do: adjust the price, cut costs or change the sales mix. This proactive approach distinguishes the future-ready operator from the passive “costing nomad” who follows old habits.
Conclusion: direction through contribution margin thinking
Switching to contribution margin costing may be a challenge at first – but it’s worth it. Instead of poking around in a fog of percentages, you gain clear direction on the profitability of your offer. Every plate, every glass becomes a contribution to shared success. Focusing on contribution margin helps you find fair prices at which neither the guest is overcharged nor the operator loses out. You spot unprofitable bestsellers and can take countermeasures before they eat up your result. You include all cost factors – from ingredients to staff – and make sure that your hospitality concept remains viable even as costs rise.
Last but not least, the CM approach strengthens entrepreneurial thinking: your team suddenly understands why upselling desserts or drinks is not just nice but necessary, and why sticking to portion sizes in the kitchen means hard cash. Together you focus on reaching the “target contribution margin” per guest in order to stay in the black. This awareness creates motivation and a sense of responsibility – everyone pulls in the same direction to be economically successful.
In summary, the message is clear: make contribution margin the key metric in your venue. Review your offer, use digital helpers for costing and, if in doubt, get coaching from experienced consultants. The days of playing with percentages are over – in modern hospitality, what counts is the bottom line. By optimising and keeping an eye on the contribution margin of every item, you set the course for a sustainably profitable and future-proof venue. Because at the end of the day, your hard work in the kitchen and front of house should also pay off in your bank account – and contribution margin is the most reliable tool for exactly that. With this in mind: good luck with CM thinking and with increasing the profit of your venue!
About the author
Lukas Graf
Managing Director